Every Plan Needs a Secure Foundation.
Explore annuity, life insurance, and long-term care solutions that strengthen your broader financial strategy.
Every retirement plan needs a foundation. For many people, that foundation is a reliable stream of income that doesn’t depend on market performance, combined with protection for the people and goals that matter most. At Summit Global Financial, we don’t start with products. We start with your goals, your timeline, and your existing investments, then identify where insurance and annuity solutions can strengthen the whole picture.

Four Pillars for a Lifetime of Financial Security

Guaranteed Income

Principal Protection & Growth

Life Insurance & Legacy

Long Term Care & Hybrid Solutions
Guaranteed Lifetime Income
Create your own paycheck for life.
When the paychecks stop, your expenses don’t. A guaranteed income strategy converts part of your savings into a predictable stream of income that can last as long as you do, no matter how long you live or how markets perform. This can cover essential expenses like housing, healthcare, and daily living, so the rest of your portfolio can stay invested for growth and flexibility.
Income solutions can begin right away or be scheduled to start at a future date, and many can be structured to cover one life or two, providing continued income for a surviving spouse.
How it can help:
- Replaces the predictable income a pension once provided
- Helps protect against the risk of outliving your savings
- Reduces the pressure to sell investments during market downturns
- Offers options for spousal continuation and legacy benefits
Principal Protection & Growth
Choose the balance of protection and opportunity that fits you.
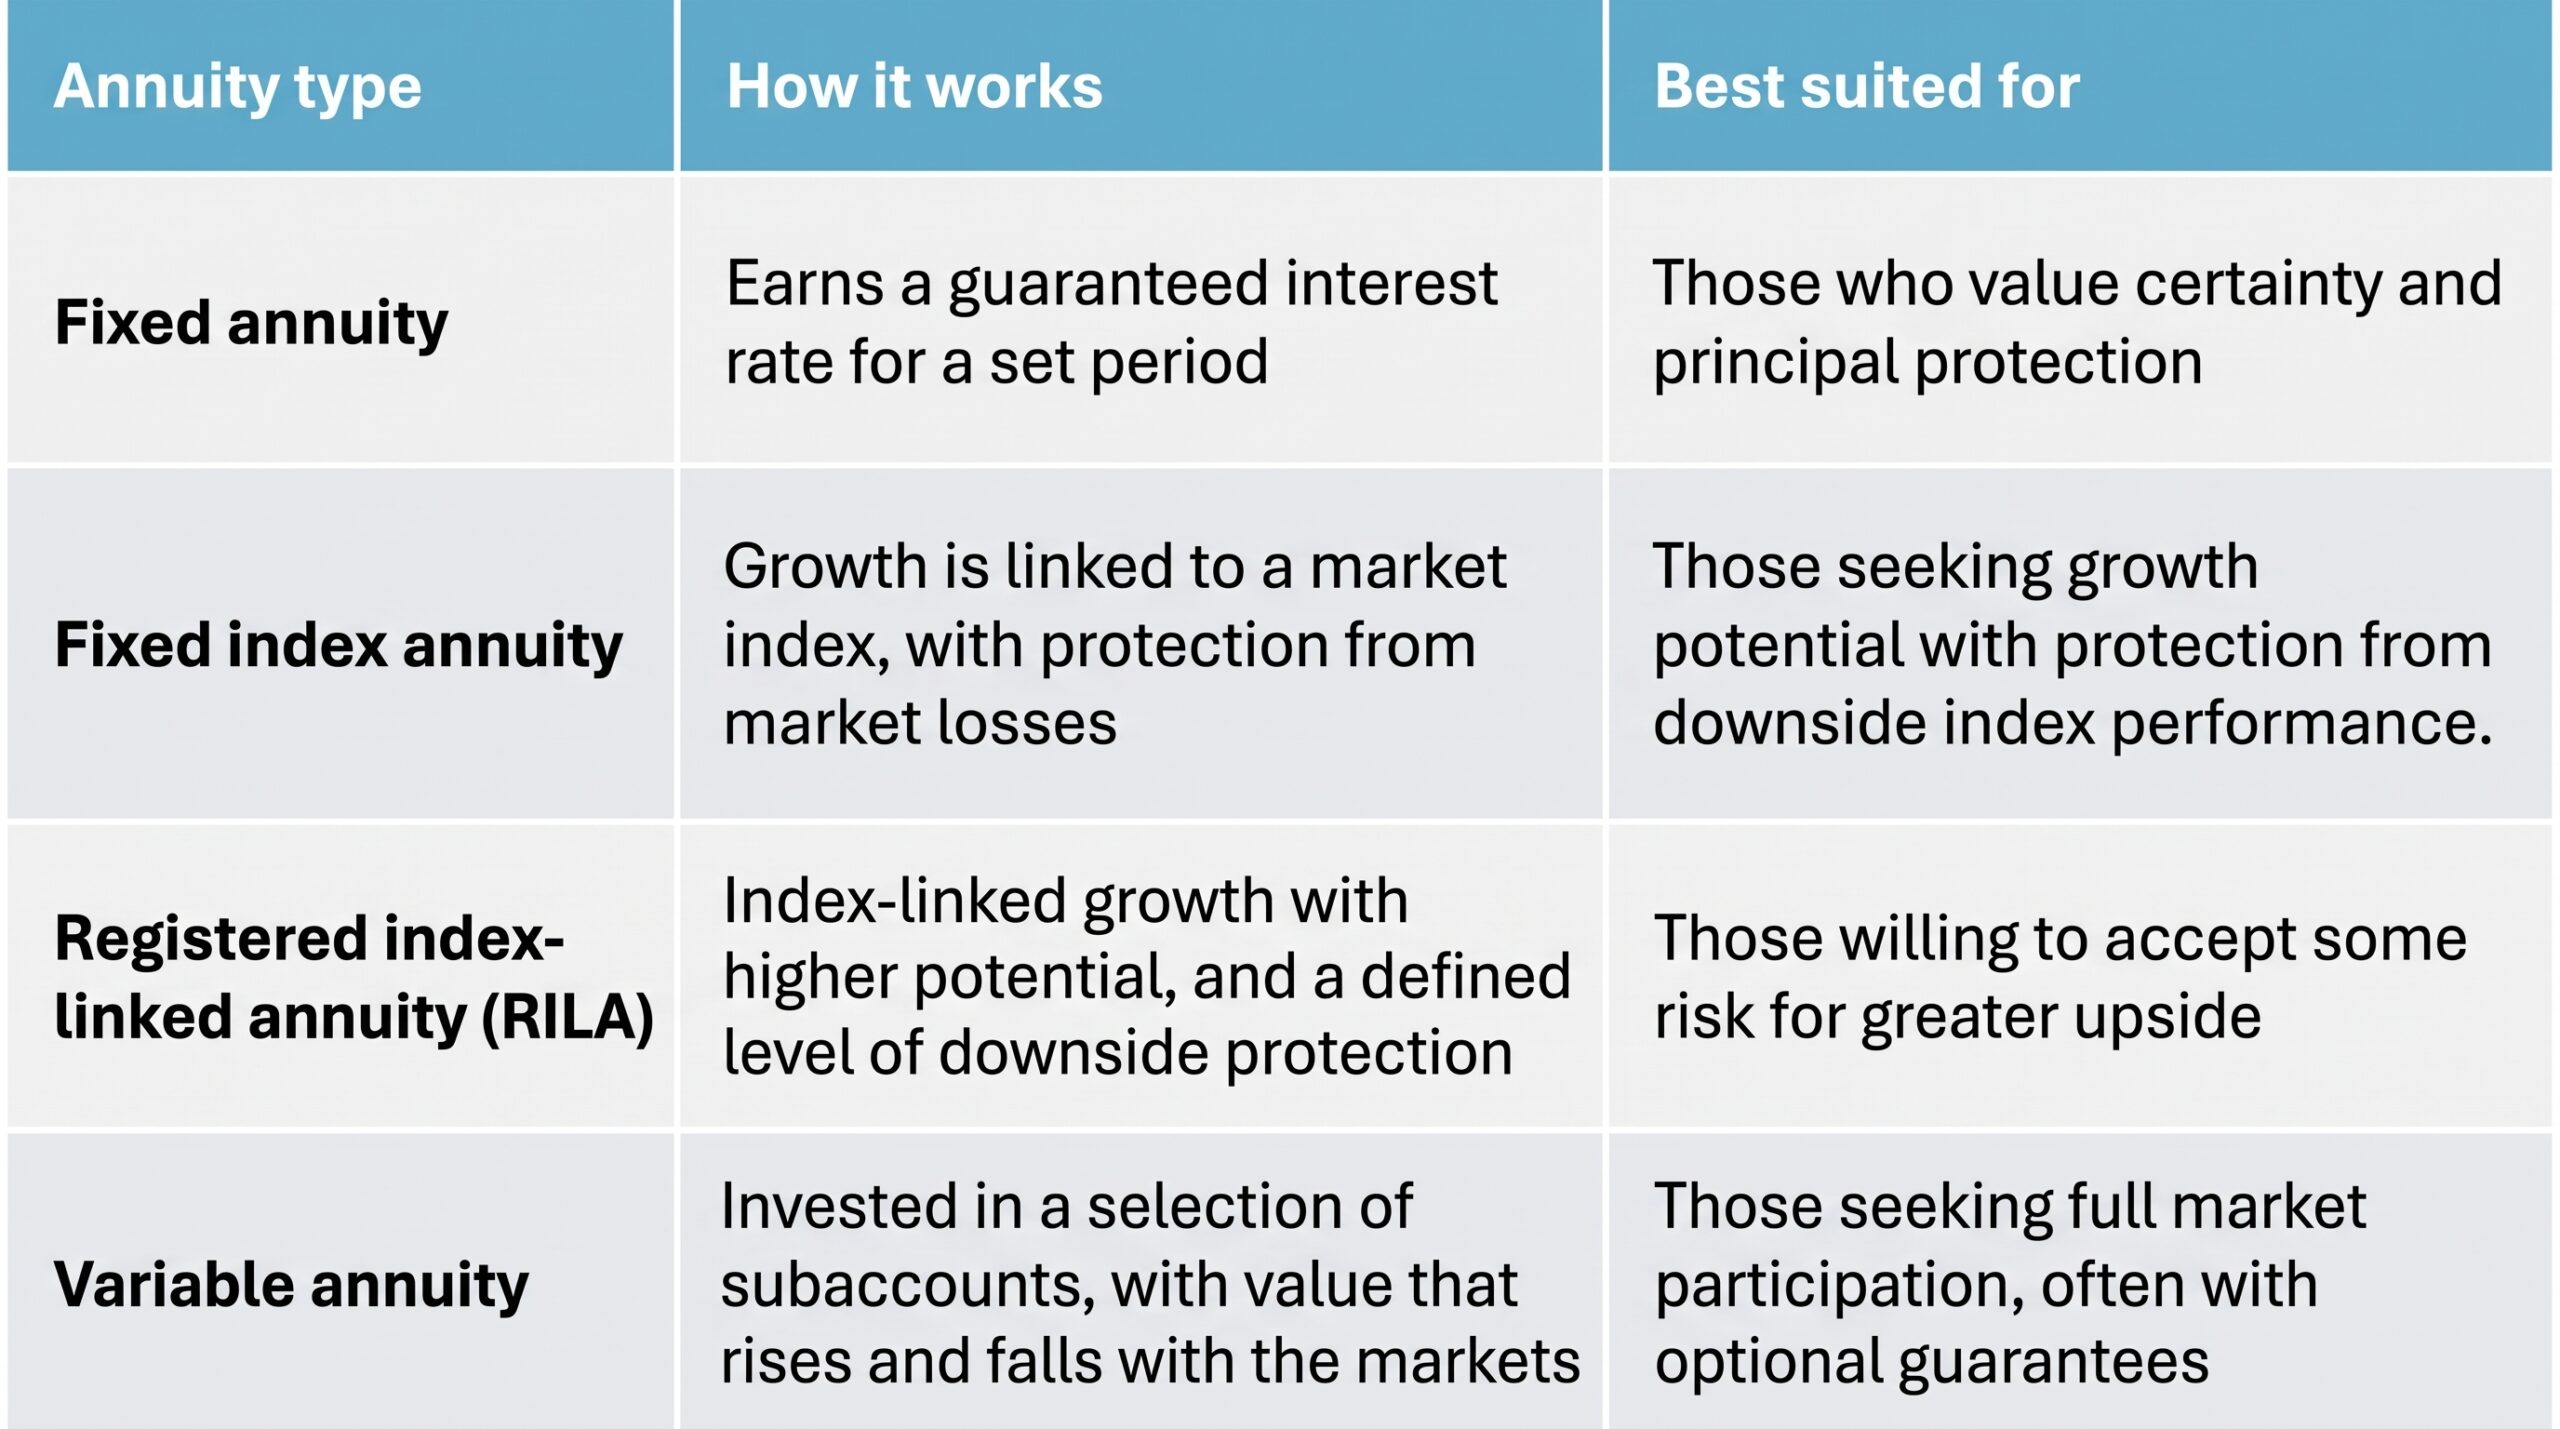
Annuities aren’t one-size-fits-all. Each type strikes a different balance between security and opportunity. Some prioritize stability, offering predictable interest and protection of your principal. Others offer more growth potential, with varying levels of market exposure and downside protection. Many can also add optional income riders that provide guaranteed lifetime withdrawals, even if your contract value declines.
The right choice depends on your time horizon, income needs, other investments, and how you feel about market ups and downs. We help you understand the trade-offs in plain language, compare options across our strategic carrier partners, and choose the approach that aligns with your goals and comfort with risk.
The comparison below offers a starting point.
Life Insurance & Legacy
Protect the people you love and the legacy you’ve built.
Life insurance is about more than a death benefit. The right policy can replace income for your family, pay off debts, fund education, equalize an inheritance, or help transfer wealth efficiently to the next generation. Some policies also build cash value over time and include living benefits that let you access funds if you face a qualifying chronic, critical, or terminal illness.
- Term life insurance: Affordable protection for a specific period, such as while children are young or a mortgage is outstanding.
- Whole life insurance: Permanent coverage with guaranteed premiums and cash value that grows on a guaranteed basis.
- Indexed universal life (IUL): Permanent coverage with flexible premiums and cash value growth linked to a market index.
- Living benefits: Riders that may allow early access to the death benefit during a qualifying illness, providing support when it’s needed most.
Long-Term Care & Hybrid Solutions
Plan for care without putting your retirement at risk.
The cost of extended care, whether at home, in assisted living, or in a nursing facility, can quickly erode even a well-built retirement plan. Planning ahead helps protect your savings, preserve your independence, and ease the burden on your family.
Today’s solutions go beyond traditional long-term care insurance. Hybrid policies combine life insurance or an annuity with long-term care benefits, so your premium dollars can provide value whether or not care is ever needed. If you need care, benefits help cover the costs. If you don’t, a death benefit or remaining value can pass to your heirs.
How it can help:
- Helps protect retirement assets from the high cost of care
- Provides more choice in where and how you receive care
- Reduces the financial and emotional strain on loved ones
- Hybrid options help address the “use it or lose it” concern of traditional coverage
Our Approach: Designed Around You
The rigor of an institutional investor, applied to your retirement income.
- Understand your full picture. We start by learning about your goals, income needs, existing investments, and concerns, so every recommendation fits within your broader plan.
- Identify gaps and risks. We evaluate where you may be exposed to longevity, market, inflation, or care-related risks, and how much guaranteed income you may need.
- Evaluate solutions objectively. Drawing on our strategic carrier partnerships, we compare options across financial strength, features, costs, and flexibility.
- Design and implement your strategy. We recommend a coordinated solution, explain it clearly, and handle the details of putting it in place.
- Review and adjust over time. As your life, goals, and markets change, we revisit your plan to keep it aligned with what matters most.